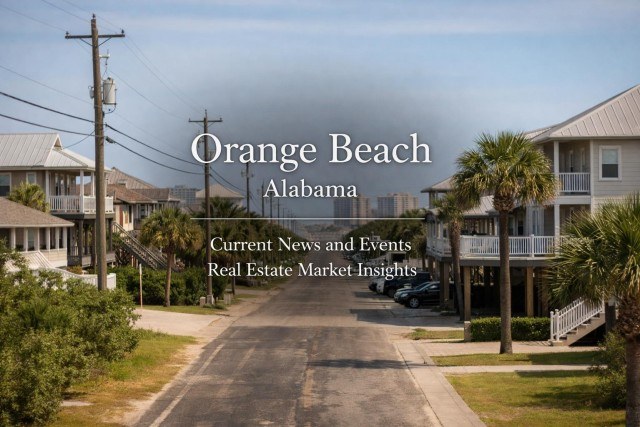
Relocation buyers planning an Orange Beach purchase should build a budget around the entire move rather than a listing price alone. The latest reported market gives a useful starting point for comparing homes, while financing, insurance, inspections, ownership responsibilities, and timing need property-specific attention.
The reported July market is classified as a buyer’s market for the combined property types. The median sold price is $737,000, with a 3.66% month-over-month decline. The median active-list price is $750,000, with a 1.2% month-over-month decline. The median estimated property value is $784,640 for August 2026. That estimated value is down 1.3% from the prior month and up 1.4% over 12 months. The latest three-month summary records 10 new properties and 10 closed properties. The market figures combine single-family and condo, townhouse, and apartment properties. Estimated values are generated by a model and are not formal appraisals. The reported figures do not include a complete budget for a specific buyer. A market median cannot establish financing approval or actual ownership costs.
A buyer’s market may create room to compare purchase prices, but affordability remains personal. The sold and list medians show why a relocation budget should use several references rather than one headline figure. An estimated value can provide context while still requiring professional property and financing review. The broader property mix means two homes at similar prices may carry very different obligations. Relocation costs can affect the comfortable purchase limit even when the contract price appears workable. More choice supports patient budgeting before a buyer commits. The strongest budget is one that remains manageable after the excitement of the move fades.
Ask a lender to review the full budget before beginning serious negotiations. Separate purchase funds from moving, inspection, repair, and reserve funds. Compare ownership obligations across the property types under consideration. Request property-specific insurance and association information when applicable. Use a conservative monthly comfort level instead of borrowing to the maximum approval. Test the plan against delayed timing or unexpected repair needs. Keep a written budget beside every property comparison and offer review.